Ever wondered why auto insurance in Massachusetts costs what it does? You’re not alone. Whether you’re a seasoned driver or new to the roads of Massachusetts, understanding the ins and outs of auto insurance can seem daunting. But fear not, because we’re here to break it down for you in a way that’s easy to digest and even easier to apply.
Massachusetts has its own unique set of rules and factors that play a role in determining your insurance rates. From minimum coverage requirements to the types of vehicles you drive, each element can significantly impact how much you’ll be paying every month. So, buckle up as we take you on a ride through the world of auto insurance in Massachusetts.
Overview of Auto Insurance in Massachusetts

Auto insurance in Massachusetts isn’t just about protecting your vehicle—it’s about meeting legal requirements and safeguarding your finances. But how do you navigate the maze of policy options and requirements?
In Massachusetts, auto insurance policies are structured with several key components. You have liability coverage, which is mandatory, and optional coverages like collision and comprehensive that protect against a range of incidents. The state mandates minimum coverage limits: $20,000 for bodily injury per person, $40,000 per accident, and $5,000 for property damage.
Minimum Coverage Requirements in Massachusetts
The state of Massachusetts requires all drivers to carry Bodily Injury to Others and Personal Injury Protection (PIP). This ensures that medical expenses and lost wages are covered if you’re injured in an accident. Additionally, Uninsured Motorist Coverage is a must, protecting you if you’re hit by someone without insurance.
Are these minimums enough? It depends. Some experts suggest higher limits to better shield your assets.
Factors Influencing Insurance Rates in Massachusetts
Here’s the deal: Your insurance rate isn’t arbitrary. It hinges on several factors, like your driving record, location, and even credit score. If you’re in Boston, expect higher rates due to urban traffic risks. Meanwhile, rural drivers might enjoy lower premiums.
Want to save a few bucks? Consider bundling your insurance or increasing your deductibles.
Pro Tip: A clean driving record is your ticket to lower premiums. Drive safely!
Cost Factors of Auto Insurance
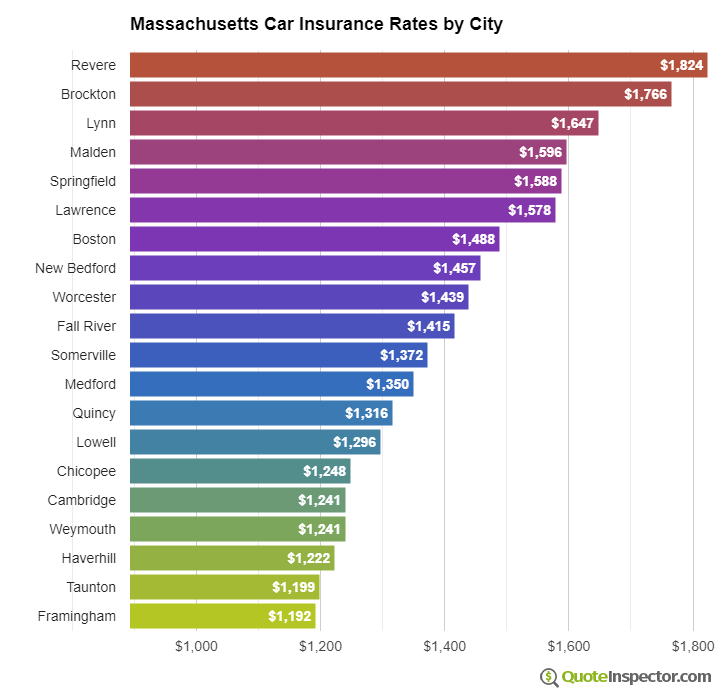
Did you know that the cost of auto insurance can vary drastically from one person to another in Massachusetts? It’s true! Several factors could make or break your auto insurance premium.
Let’s dive into the details of what influences these costs and how you can strategically manage them.
Impact of Driving History on Insurance Premiums
If you’ve ever wondered why your insurance bill is so high, look no further than your driving history. Insurance companies in Massachusetts scrutinize your record with a magnifying glass. Have a speeding ticket or an accident? You’re likely paying more. But here’s the deal: maintaining a clean record can save you up to 30% on your premiums. It’s not just about avoiding points on your license; it’s about keeping more money in your pocket.
The Influence of Vehicle Type and Age
Believe it or not, your car’s age and model play a starring role in determining your insurance costs. Own a brand-new sports car? Brace yourself for higher rates. On the flip side, an older, less flashy vehicle might be your ticket to more affordable coverage. But that’s not all. The vehicle’s safety features and repair costs also factor into the equation. Pro Tip: Investing in a car with advanced safety features can
significantly reduce your insurance premium
. It’s a smart move that pays off over time.
Primary Factors Affecting Auto Insurance Costs
Several elements influence what you pay for auto insurance in Massachusetts. Here are the big players:
- Your driving record: Clean vs. violations.
- Vehicle type: Sports car vs. family sedan.
- Location: Urban vs. rural areas.
- Coverage level: Basic vs. comprehensive.
- Credit score: Higher scores can mean lower rates.
Each of these factors interacts to determine your unique rate. By understanding and managing these elements, you can find effective ways to keep your auto insurance costs in check.
Types of Coverage Options
Did you know that the average driver in Massachusetts could be underinsured? That’s a scary thought, especially if you’re involved in an accident. Let’s break down the different types of auto insurance coverage available.
In Massachusetts, you have several options when it comes to auto insurance. The basic types include liability, collision, and comprehensive coverage. Each serves a different purpose, and choosing the right mix can save you a ton of money in the long run.
Understanding Liability, Collision, and Comprehensive Insurance
Liability insurance covers the other party’s damages if you’re at fault in an accident. It’s the minimum requirement in Massachusetts, but don’t let that fool you into thinking it’s all you need. Liability won’t cover damages to your own vehicle.
On the other hand, collision insurance takes care of the repair or replacement of your car after an accident, regardless of who caused it. Think of it as a safety net for your own vehicle.
Then there’s comprehensive insurance. This covers non-collision-related incidents like theft, vandalism, or natural disasters. Imagine finding your car under a fallen tree—comprehensive is what you need there.
Additional Coverage Options and Their Benefits
Beyond the basics, there are additional coverage options that can offer extra peace of mind. Consider these as the add-ons that many drivers find invaluable.
- Uninsured/Underinsured Motorist Coverage: Protects you if you’re hit by someone who doesn’t have enough insurance.
- Personal Injury Protection (PIP): Covers medical expenses for you and your passengers, regardless of fault.
- Rental Reimbursement: Pays for a rental car while your vehicle is in the shop after a covered incident.
- Roadside Assistance: Provides services like towing, flat-tire change, and jump-starts.
Pro Tip: Always evaluate your specific needs and driving habits when choosing coverage options. The right mix can save you thousands!
Finding Affordable Insurance
Did you know that auto insurance rates in Massachusetts can vary by as much as 40% for the same coverage? That’s a massive difference. Whether you’re a new driver or a seasoned pro, navigating these rates can be a challenge, but it’s not impossible.
Here is the deal: You don’t have to settle for sky-high premiums. With a few savvy strategies, you can significantly cut down your insurance costs without skimping on coverage.
Methods to Reduce Auto Insurance Premiums
If you’re tired of overpaying for your auto insurance, you’re in the right place. The first step is understanding what factors impact your rates. Your driving record, credit score, and even your car’s make and model all play a part. But how can you reduce these premiums effectively?
- Compare quotes from multiple insurers. Massachusetts has a competitive insurance market. Use it to your advantage.
- Consider raising your deductible. A higher deductible can lower your premium significantly.
- Maintain a good credit score. Insurers often use credit information to price auto policies.
- Bundle your policies. Many insurers offer discounts if you have other types of insurance with them.
Pro Tip: Some insurers offer discounts for low-mileage drivers. If you don’t drive often, make sure to inquire about this discount.
Tips for Comparing Insurance Quotes Effectively
When was the last time you compared insurance quotes? If it’s been a while, you’re likely leaving money on the table. The key is not just to compare, but to compare effectively.
- Always get quotes from at least three different companies. More options mean better chances of finding a deal.
- Use online comparison tools to streamline the process. They can give you a quick snapshot of who’s offering the best rates.
- Check for hidden fees or charges that might not be obvious at first glance.
- Ensure you’re comparing apples to apples. Make sure each quote includes the same coverage types and limits.
Strategy for Negotiating Better Insurance Rates
Think negotiating is just for buying cars and houses? Think again. You can negotiate your insurance rates too! Start by having a clear understanding of your current policy and market rates.
Here’s how to do it:
- Gather quotes from competitors and present them to your current insurer. Use them as leverage.
- Ask for all available discounts. Sometimes, all it takes is asking.
- Review your coverage annually. Circumstances change, and so should your insurance.
- Be ready to switch if negotiations don’t lead to a better rate. Loyalty is valuable but not at the expense of your wallet.
Insurance Providers and Ratings
Ever wondered which auto insurance companies in Massachusetts come out on top? Choosing the right provider isn’t just about price—it’s about trust.
When it comes to auto insurance, customer service and claims handling are critical. Imagine getting into an accident and not getting the support you need. Nightmare, right? That’s why looking beyond premiums can save you headaches down the road.
Top Auto Insurance Providers in Massachusetts
Here’s a rundown of the top-rated auto insurance companies in Massachusetts based on customer feedback:
| Insurance Provider | Customer Rating (out of 5) |
|---|---|
| Geico | 4.7 |
| Progressive | 4.6 |
| Liberty Mutual | 4.5 |
| State Farm | 4.4 |
| Allstate | 4.3 |
The Role of Customer Service and Claims Handling
Ever had a frustrating customer service experience? The truth is, it can make or break your relationship with your insurer. Speedy claims handling and responsive customer service are must-haves.
Here is the deal: great insurance isn’t just about low premiums. It’s about knowing that they’ll have your back when things go south. That’s why checking reviews and ratings is crucial.
How to Evaluate Insurance Provider Reputations
Step #1: Head to online review sites. These can give you a sense of what other customers are saying.
Step #2: Look for consistency. One bad review isn’t a deal-breaker, but a pattern of complaints might be.
Pro Tip: Check the company’s financial strength too. A stable company is more likely to handle claims effectively.
Remember, analyzing these factors will guide you to the right provider that fits your needs. After all, peace of mind on the road is priceless.
Legislative and Regulatory Factors
Did you know that state laws can significantly impact your auto insurance costs? It’s true. In Massachusetts, these regulations are not only complex but they *directly influence* what you pay for auto insurance.
State legislation shapes everything from minimum coverage requirements to the way insurers calculate risk. Regulatory changes can shift the landscape, affecting policy terms and rates almost overnight. Understanding these factors is crucial if you want to navigate the auto insurance market effectively.
Impact of State Laws on Insurance Costs
Massachusetts mandates specific minimum coverage levels for all drivers. This means you can’t skimp on certain types of coverage if you want to stay legal. While these laws ensure protection, they also drive up costs compared to states with lower minimums. But here is the deal: higher minimums can save you from financial disaster in an accident.
Legislative trends also aim to introduce new requirements, like extended personal injury protection. Such changes can catch you off guard, leading to unexpected hikes in your premiums.
Regulatory Changes and Policy Terms
Regulations in Massachusetts are dynamic, often responding to economic and social needs. Recent years have seen regulatory bodies pushing for more consumer-friendly policies. While this is great news for you, it can mean recalibrations in how insurers price their policies. Insurers must adapt to these changes, sometimes resulting in temporary rate increases.
Keep an eye on proposed legislation, as changes can affect your coverage options and costs. Pro Tip:
Stay informed about pending bills in the Massachusetts legislature that could impact auto insurance. This keeps you a step ahead of potential price hikes.
Current Legal Trends in Massachusetts
A hot topic today is the regulation of ride-sharing services like Uber and Lyft. Massachusetts is considering laws that would require additional coverage for drivers engaged in these activities. If passed, the legislation could set a precedent, affecting how insurers price policies for gig economy participants.
Another trend is the push for more stringent enforcement of existing laws, which could mean tougher penalties for uninsured drivers. This could ultimately lead to a reduction in uninsured motorist premiums, benefiting you in the long run.
Last Word
In conclusion, understanding the cost of auto insurance in Massachusetts is about more than just numbers. It’s about knowing what factors influence your rates and how you can leverage them to your advantage. By considering the tips and insights we’ve shared, you’re now equipped to navigate the world of auto insurance with confidence. Remember, the road to affordable coverage is paved with knowledge!
FAQ
What is the minimum auto insurance coverage required in Massachusetts?
Massachusetts requires drivers to have a minimum coverage of $20,000 per person and $40,000 per accident for bodily injury, and $5,000 for property damage.
How does my driving history affect my insurance premium?
Your driving history is crucial; a clean record can lower your premiums, while accidents or violations may increase them.
Does the type of car I drive impact my insurance rates?
Yes, the make, model, and age of your vehicle can significantly influence your insurance costs. Generally, more expensive or newer cars may lead to higher premiums.
Are there ways to lower my auto insurance costs in Massachusetts?
Absolutely! You can reduce costs by shopping around for quotes, maintaining a good driving record, and considering higher deductibles.
Which are the top auto insurance providers in Massachusetts?
Some of the top providers include Geico, Progressive, and Liberty Mutual, known for their strong customer service and claims handling.
